


Feelings in Finance—Your Empowerment Guide
Feelings in Finance—Your Empowerment Guide
 People often treat money like it’s numbers and facts. And then they judge themselves for not making good money decisions. It becomes a vicious cycle: “I’m not good with numbers, so I’m not good with money.” Unfortunately, those feelings about finance are a self-fulfilling prophecy.
But what if there was a different way? What if you connected to your emotions surrounding money and that helped you actually master your finances?
Money and emotions are deeply connected. We all have money stories that we tell ourselves to justify our behavior. A lot of us assumed that money was just math. And we were illogical or bad with money because we were bad with math. While that’s a common narrative, it’s not a helpful narrative.
The goal of this article is to help you see thinking traps that you stumble upon with your money and provide a different way of thinking about things.
Money is a complex topic, but hopefully, this guide will leave you feeling confident to tackle your money from a new perspective. We want you to build your wealth so that you can live a fuller, happier life.
Key takeaways:
- Start with small steps and work toward large financial change.
- Long-term wealth building starts with changing the way you think about money.
- Anyone can learn to be good with money.
Keep Focused on Long-term Wealth Building
In order to build wealth successfully, you’ll want to keep focused on long-term wealth building. This can get emotional when you think about the money stories that you tell yourself. Sometimes we don’t believe that we’re good enough to be rich, so we self-sabotage. We spend money that we don’t have so we can stay poor because that’s what we believe we should be. It’s hard to break that cycle because you need to start believing and respecting yourself. This is not easy, especially if you’ve spent a lifetime disrespecting yourself. Taking baby steps is a good place to start. Have an attainable goal, maybe that is saving $20 in a month. It seems tiny, but if you’ve spent years burning through paychecks, it’s going to be hard. That’s okay. You can break it up into two ways: either save $5 every week or save $10 every paycheck.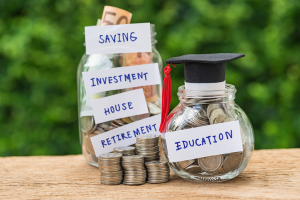 The goal here is to ensure the habit of sustained attention is being built. I’d recommend putting it into a different savings account that is harder to access to make the savings last. If you’re able to save $20 in a month successfully, try saving more (maybe $40) the next month. Break it up in a way that makes sense to you, either $10 a week or $20 a paycheck.
Pro tip: Create savings rules in your bank account so that the money is automatically transferred. You’re more likely to save money if you don’t have to transfer the money every time. It keeps you from forgetting or talking yourself out of saving money because things feel tight. And more often than not, you won’t miss the money you’re saving if it’s automated.Avoid the trap of getting overzealous when you first start to realize you can save money. Don’t be so focused on saving that you "over-save" and can’t pay your bills. That will backfire and create more problems. You’ll have to pull money out of savings, which creates the sense that savings can be used regularly. When saving is new, it’s hard—especially if you have to touch the cash you put into the account. Instead, start with small, attainable goals and gradually build the muscle of saving.
Create a Long-term Money Goal and Stick With It
Long-term wealth creation starts with a budget that you can follow through on. The word budget comes with all this stigma and bad vibes. But I want you to stop thinking of a budget as a prison sentence and instead think of a budget as a tool to help you reach your goals. Take a moment to dream about goals that you think are impossible but that you really want to do. Take some time to hammer out those details. How much money will it take to accomplish this goal? Use clear, concrete goals. Say you want to take 6 months to backpack around Europe. It’s going to cost $10,000. And you want to go in five years. That means you need to save $2,000 each year, or $165 a month. Work that into your budget. All of a sudden, your big dream has been broken down into smaller metrics that are attainable. That’s what good budgeting is.
Now, $165 might not be feasible with the money you have coming in. You might have to extend your timeline. Or, you can pick up a side hustle to find that money. But the goal is to look both short- and long-term at your money to design a lifestyle that you love.
Your job is to create a budget that fits those needs (rent, groceries, bills) and wants (new clothes, accessories, trips) and then stick to that budget.
Pro tip: Track your spending to help keep your long-term goals at the forefront of your mind.Maintaining your budget is the hardest part of money management since it takes some level of discipline. Tracking your monthly spending can help you slow down your spending and divert cash from your impulse purchases to your long-term goals.
Learn to Keep Your Spending in Check
Another way we use our money is as a coping mechanism for life’s difficulties. When we’ve had a bad day at work, we might stop by the bar on the way home and drink a few beers. Or if we’re stressed with a big problem, it can feel good to order something online. For many of us, spending money feels good. It isn’t inherently wrong to spend money to cope with life—if you budget for it appropriately. If you’re spending outside of your budget and find yourself short on bill money, it’s time to reassess your situation. Figure out your spending triggers. Keep a diary of your spending. Anytime you make a purchase outside of your usual budget (i.e. food, gas, groceries, and any other essentials), write down how you felt about the purchase and if there were any events preceding the purchase that were stressful. If you do this for a month or two, you’ll have a pretty good idea of where you spend money emotionally. Now comes the hard part. You’ll need to come up with free, compatible substitutes for those moments when you really want to spend money. If you buy a latte every time you have a bad day at work, you might want to invest in a medium-scale espresso machine at home to get the same fix, but for a fraction of the price. If you buy clothes every time you get into a fight with someone, consider other ways to make you feel good about yourself. Having a prepped self-care shelf in your bathroom might help you pamper yourself, but at home. I’m not recommending that you cut out all discretionary spending. That will lead to financial burnout. But I am suggesting you take the time to focus on problem points in your spending and help curb some of the emotional spending you may be doing.
Pro tip: Learn to gamify your money in small ways, and it will be easier to save money in the long run.Create a goal for yourself—something reasonable. Say you want to take a mini vacation or book a spa day. Decide how much you need to save for that. Let’s say it's $300-$500. Every time you want to spend money, put the amount you would have spent into a dedicated savings account. It might take a few months, or a year, but eventually, you’ll have the money saved for your trip. This does two things. It satisfies your need to do something impulsive. Money is being moved. But it also teaches you how to save for a short-term goal.
Find a Financial Rhythm That Works for You
Finding a financial rhythm is difficult. It’s a balancing act between needs and wants. At first, that might feel laborious. It’s hard to learn to budget appropriately for everything in your life. But it’s the key to financial success. You’ll have to work with yourself to see the financial results that you want. That means approaching finances with a strategy in mind. Using different budgeting methods to approach your finances will help you determine the way you work best with money. You might want to use zero-based budgeting, where every dollar has a specified purpose. You might find that too restricting and do a 20/30/50 split, where 20 percent of your money is saved, 30 percent is discretionary, and the last 50 percent is for essentials. You might choose the cash envelope approach, where you section out all your money into cash and spend out of envelopes to keep problem spending areas in check. When you’re first finding your financial rhythm, it will feel clunky. It will take a long time to figure out what works for you, and you’ll spend a lot of time struggling to make the numbers work the way they need to. Keep up hope, though, because the longer you do it, the easier it will become.Pro tip: try a different budgeting style each month until you find one that fits best for you and your family.
Learn to Be Flexible with Your Money
A huge benefit of money management is learning to be flexible with your money. Money is the best barrier between you and stressful life situations. Money doesn’t solve everything, but it’s a very effective tool that you can use when addressing a problem. If you’re rigid with your money, then you won’t be able to roll with the punches of life. What does money flexibility look like? It starts with flexibility in your budget. While it might seem like budgeting down to the last penny is helpful, you can actually do more harm than good this way. Small emergencies pop up every month, and you want to be prepared for them. You drive more miles than you were anticipating and you need an oil change sooner than expected. If every single cent of your money is going somewhere, then you won’t be prepared to spend $50-$60 on your car.
Pro tip: build a short-term emergency fund into your monthly budget to handle life’s small unexpected expenses.I recommend building flexibility into your budget. I have $200 each month that I can spend on life’s mishaps. I’ve used it to buy a shirt when I spilled coffee on mine on the way to an important presentation. I’ve used it to fly a friend out when she was having a really rough time. I’ve used it on more car tires than I care to admit. I have an affinity for getting flats. If there’s money left over at the end of the month, I put it toward my short-term savings goals. And then the next month starts back with a $200. Some people aren’t comfortable putting it towards a fun goal, so they pad their emergency fund with the extra money. That’s part of the beauty of flexibility with money. You do what’s right for you in your situation regardless of what you think is expected of you.
Know You Can Change Your Mind on Money Issues
Similar to building flexibility into your budget, you’ll also want to be flexible on how you think about money issues. Knowing you can change your mind as your life changes gives you the freedom to make money decisions that fit your lifestyle as you grow. At some point in your life, you might want a smaller emergency fund. Say you’re living at home and have few necessary expenses. It might make sense to only keep $3,000-$5,000 in your emergency fund and then invest more heavily in the market. But when you move out, your situation might not stay the same. You might feel more secure with a $10,000-$15,000 emergency fund. Maybe at the beginning of your professional career, you really wanted to buy a home, so you saved a down payment. However, you decided once you had the money saved that you didn’t want to buy a home. It’s okay to move that money towards a goal. You’re not stuck with the financial goals you started with. You’re allowed to change them to fit where you are in your current form.Pro tip: Being flexible with money allows you to have more financial freedom in your life.
FAQs
How Can I Develop Better Money Skills?
Developing strong money skills starts with determination. You have to commit to developing the skills. At first, you’re not going to be very good at it. Give yourself permission to try things that seem scary because you don’t know if you’re going to be good at them. And from there, practice continuous smart money development—just keep getting better. If you need accountability, consider joining a money group. Facebook is a great place to find one, and you can even look for local chapters in your area that have meet-ups. You could even sign up to lead a money group!How Much Should I Actually Be Spending on Fun Stuff?
This depends on your budget. A good rule of thumb is to save 20%, spend 50% on needs, and 30% on wants. But if you’re not making enough to cover your living expenses on half of your salary, you’re going to need to reconfigure this number. And that’s okay. The important thing is that you’re not overspending on fun things. Make sure all your basics (savings and essentials) are covered and have fun with the rest! How Do I Balance Short-Term and Long-Term Financial Goals? One of the hardest things when you first start savings is learning to balance those short-term and long-term financial goals. I focus on one goal at a time, until I develop a habit, and then I start another goal. For instance, I wanted to save 15% for retirement, and then save $100 a month for a trip I was taking. Saving for the trip was first, so I budgeted $100 a month for three months before I added in the 15% for retirement. That way I was comfortable with my new budget. When the trip is over, I can apply that $100 a month to another goal without overwhelming my budget. Do you know the #1 Tradeline Secret?
Use the secret to unlock your full tradeline power.
Use the secret to unlock your full tradeline power.
Author
Moriah Chace is an award-winning, queer Gen Z author known for promoting financial literacy. Moriah's financial articles have appeared in The Motley Fool, Buzfeed, Bankrate & Bigger Pockets, Moriah is a leading voice in helping people take control of their finances. As a lover of all things DIY, she spends her free time fixing up cars from the 90s and vintage RVs.
BROWSE ALL CATEGORIES
LATESTCREDIT VENDOR RESOURCESLEGAL & ETHICAL TOPICSCREDIT REPAIR & CREDIT SCORE INFORMATIONTRADELINE RESOURCESCOMPANY NEWSGUEST ARTICLES BY CREDIT EXPERT JOHN ULZHEIMERINFOGRAPHICSPERSONAL FINANCECREDIT COUNTDOWN VIDEOSCREDIT CARDSLOANSBUSINESS CREDITBROKER PARTNER RESOURCESARTICLE
Related posts
How to Improve Your Financial Situation With Extra MoneyHow to Protect Your Finances as a Pet ParentHow to Deal With Holiday DebtHow to Use Credit Cards Responsibly Without Going Into DebtHow to Improve Your Finances in 2025Debit vs. Credit Cards: Which Is the Better Way to Pay?What Is Buy Now Pay Later and How Does It Affect Your Credit?4 More Master Money Habits for Wealth: Essential Money Cognitive Ca...Four Best First Money Habits to MasterLine of Credit—Essential Guide to Expectations & Realities
Comments (0)
Comments (0)
MOST POPULAR ARTICLES
- How to Choose a Tradeline: A Buyer’s Guide
- Common Mistakes Made When Buying Tradelines
- Tradelines 101 [Infographic]
- Credit Repair vs. Tradelines [Infographic]
- Tradelines: What You Should Know About Building Credit
- How Many Tradelines Do I Need?
- What Happened to Equal Credit Opportunity for All?
- The #1 Secret on How to Unlock the Power of Tradelines
* Tradeline Supply Company, LLC does not guarantee credit score improvement. We provide a tradeline marketplace platform. Tradeline non-postings may occur and will result in a refund or exchange.